
Modern retirement planning – individual, cost-efficient, predictable
We don’t believe in compromises.
Least of all when it comes to your standard of living in retirement.
It is already clear to everyone today that the German statutory pension will not be enough. We help you achieve financial independence in retirement. For many people, retirement provision is their biggest investment – together, we plan the best way forward with you.
Retirement calculator
Your pension gap – and what it costs to close it
Set your assumptions. The calculator shows live how much capital you need, which monthly savings rate is required – and what you can actually achieve with the amount you are able to save.
Assumptions
Set your parameters
Simplified model for orientation only – not investment or tax advice. All values are nominal unless stated otherwise.
Target pension at retirement
€6,856
€4,800 today · 2.0% inflation
Eligible pensions at that point
€4,124
net, nominal
Gap to close
€2,732
monthly, nominal
Capital required
€851k
€850,673 · drawn down over 32 years
Required savings rate
€584
constant over 18 years
Total own contributions
€126k
Investment returns: €177k
Capital over time: build-up and drawdown
Nominal values. The peak marks the start of retirement.
Reality check
The reverse calculation: what can you actually achieve with a given savings rate?
Capital at retirement
€807k
nominal
Achievable income
€4,702
monthly, today’s purchasing power, incl. pensions
Goal reached. With this savings rate, your desired standard of living in retirement is achievable.
You benefit from our independent advice and expertise.
We select a cost-efficient and flexible product for you. That is the only way you will reach your goal. Traditional insurance and banking products often have excessively high acquisition and administration costs. We advise you for a fee, free from commission pressure, and arrange transparent net-cost solutions.
Free initial consultation, including a status check of your existing contracts and portfolios.
Suggest an appointmentOur long-term investment strategy balances opportunities and risks. Based on scientific findings, we develop an individual retirement plan for you that reflects your investment horizon and risk appetite. Predictable, flexible and tax-optimised.
Modern retirement planning with equity funds – evidence-based, diversified, cost-efficient
Our recommendations follow an evidence-based, rules-based approach: we rely on broad market indices and systematic tilts towards scientifically well-documented risk premiums (e.g. company size, valuation, profitability). This way, you capture expected excess returns not through gut feeling, but in a structured and disciplined way. Practical implementation and cost control are key: consistent rebalancing, careful order and liquidity management, low total costs and – where appropriate – tax-efficient structures. Regular review meetings ensure that you have a dedicated point of contact and that we carefully adapt your portfolio to your life situation and goals. If you wish, you can integrate your own ETFs; switches are flexibly possible within the chosen structure. You also gain access to institutional share classes of rules-based funds on favourable terms that are often not available in a conventional private portfolio.
Around ten years before your planned retirement, we gradually reduce risk and shift parts of your assets into high-quality bonds to dampen fluctuations and stabilise your ability to draw an income. When retirement begins, you remain flexible: predictable withdrawal plans as a monthly supplementary pension, partial withdrawals with the remaining capital still invested, or a full payout – each tailored to your liquidity, taxes and need for security.
Let the markets work for you
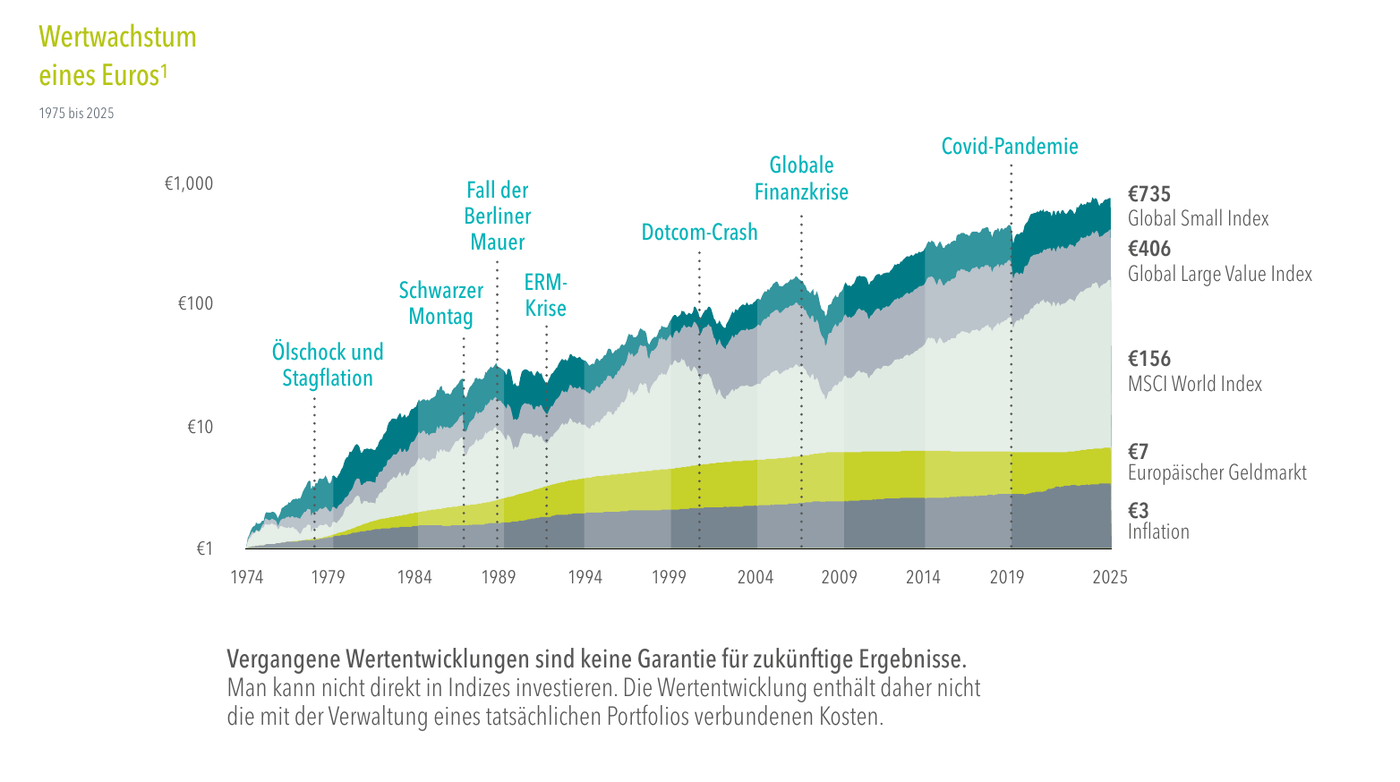
Daily headlines test every investor’s discipline – yet over the long term, the equity and bond markets have above all been one thing: a long story of growth. If you invest broadly diversified and stay invested, you let exactly this development work for your own wealth building.
Personal advice – strategy instead of product sales
Choosing the right investment strategy raises many questions. We structure your retirement provision with clear building blocks (ETFs/funds), transparent costs and a predictable management process – whenever and wherever suits you.
Suggest an appointment